
To check agency retainer profitability, add the retainer and agreed change fees, subtract the labor and direct expenses used to serve that client, then divide the remaining contribution by those fees. Review delivery hours separately: exceeding scope does not automatically create billable revenue or prove that an account is unprofitable.
This walkthrough uses fictional client-months from the TemplateBase planner. It shows how to distinguish a scope warning from a pricing gap, what to collect before changing a fee, and how to avoid treating incomplete time records as healthy margins. Figures are illustrative USD amounts, not agency benchmarks or customer results.
What does a retainer profitability calculation include?
Use one client and one month as the reporting unit. Keep the period, currency and cost policy consistent. For the operating view used here:
- Client fees = retainer fee + agreed change-request fees.
- Labor cost = the sum of each person’s logged delivery hours × that person’s burdened hourly cost.
- Direct cost = labor cost + other client-specific direct expenses.
- Direct contribution = client fees − direct cost.
- Direct margin = direct contribution ÷ client fees.
Burdened hourly cost should follow a documented policy for compensation or contractor cost and relevant employment costs. A selling rate is not a labor cost rate. If a person changes roles or rates, confirm that the rate used matches the work being reviewed.
This is a deliberately limited operating view. It excludes agency overhead, taxes, collections, refunds and owner distributions. It does not establish accounting net income or cash in the bank. A positive client contribution can coexist with an agency-level loss.
Worked example: more fees, less contribution
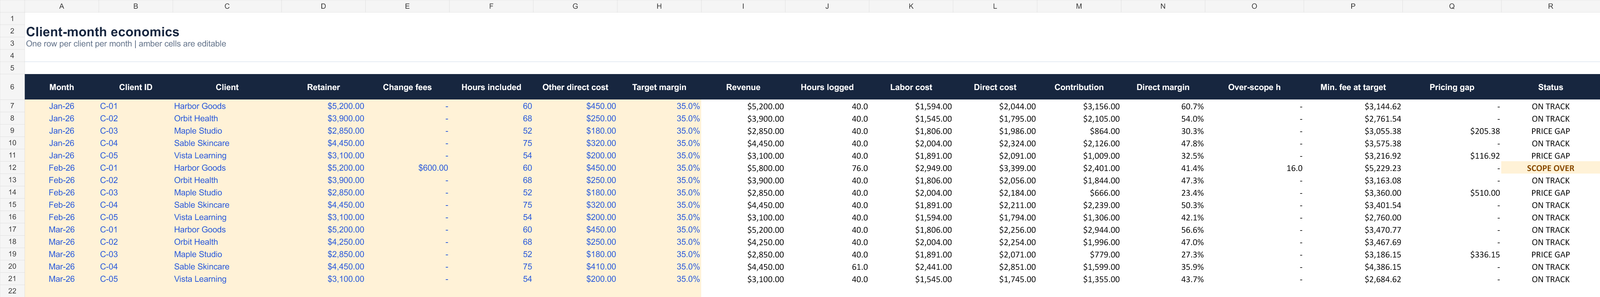
Harbor Goods is a fictional retainer client with 60 included hours each month. In February the agency agrees to an additional $600 fee, but delivery effort also increases.
| Measure | January | February |
|---|---|---|
| Retainer fee | $5,200 | $5,200 |
| Agreed change fees | $0 | $600 |
| Total client fees | $5,200 | $5,800 |
| Hours logged / included | 40 / 60 | 76 / 60 |
| Labor cost | $1,594 | $2,949 |
| Other direct cost | $450 | $450 |
| Direct contribution | $3,156 | $2,401 |
| Direct margin | 60.7% | 41.4% |
| Hours above included scope | 0 | 16 |
The February labor cost is 23 hours × $39 + 28 hours × $34 + 25 hours × $44 = $2,949. Adding $450 of other direct expenses gives $3,399 of direct cost. Subtract that from $5,800 of fees to get $2,401 of direct contribution.
Fees increased by $600, while labor cost increased by $1,355. Contribution therefore fell by $755. Both hours and the mix of people doing the work matter; an average selling rate would not explain the cost change.
The 16 extra hours are a scope warning. They are not another invoice. The $600 change fee is already included once in the fee total; adding it again would overstate income. Check what the agreement covered and which work was approved before proposing any commercial change.
A scope warning and a pricing gap are different
Suppose the agency selects a hypothetical 35% target direct margin. This is an example assumption, not a recommended industry target. Holding the February cost base fixed, the fee implied by that target is:
Fee at target margin = $3,399 ÷ (1 − 0.35) = $5,229.23.
The actual February fees are $5,800, so this account has no positive pricing gap against that particular target. It remains above the target while exceeding its included hours. Investigate scope and delivery consistency, but do not conclude that the spreadsheet has proved a fee increase is necessary.
Now consider a different fictional client-month: Maple Studio in March. Fees are $2,850 and direct cost is $2,071. Contribution is $779, giving a direct margin of 27.3%. At the same illustrative 35% target, the implied fee is $2,071 ÷ 0.65 = $3,186.15. The positive gap from actual fees is $336.15.
That figure is a cost-based planning result, not a quotation the client has accepted. A different scope, staffing mix or negotiated fee changes the calculation. Review what customers value, your delivery choices and the commercial agreement before acting.
Why cost × 1.35 does not produce a 35% margin
Margin divides the difference by revenue; markup divides it by cost. For example, $3,399 × 1.35 gives a price of $4,588.65. Its margin is only 25.9%, because $1,189.65 ÷ $4,588.65 is approximately 25.9%. Xero’s margin versus markup explanation describes this denominator distinction. Keep the terminology consistent in your proposal and spreadsheet.
A monthly review you can repeat
- Reconcile the source records. Compare the time log with the records your team actually uses. Confirm that every relevant person and work entry is included. A workbook cannot warn about work that was never entered.
- Resolve missing inputs. Check client IDs, team IDs, month-start dates, rates, direct expenses and duplicate client-months. Enter zero for a true zero; a blank required expense is not evidence that the client incurred no expense.
- Read account-level results. Review contribution, direct margin, hours over scope and the cost-based pricing gap together. One status label cannot show every issue.
- Discuss the reason. Was the extra effort caused by approved scope, revision rounds, rework, a staffing change or an inaccurate estimate? Connect the numbers to the work instead of assuming the customer caused every overrun.
- Choose and document the next step. Agree who will clarify scope, improve a process, revise staffing or prepare a fee discussion. Record an owner and review date. Recheck actual delivery in the following month.
Harvest’s guide to project pricing models also discusses using time records to support retainer discussions as work changes. The records support the conversation; they do not replace the agreement.
Use the worked example in an editable workbook
The Agency Retainer Profitability & Capacity Planner includes the fictional client-months above, a matching blank Excel workbook, a three-page guide and an editable dashboard. It links client fees and scope to team rates and logged hours, with separate columns for contribution, over-scope hours and pricing gaps.
Version 1.1 checks missing or invalid month-start dates and incomplete source rows. Dashboard totals remain unavailable while REVIEW records are unresolved, including records in other months. A no-data report month is shown separately from zero results. The prebuilt ranges cover 60 client-months, 300 time entries and 12 people.
It is designed for Microsoft Excel and manual data entry. It does not connect to a time tracker, generate invoices or reserve future capacity. Team capacity is a fixed monthly input; the chart displays January–June 2026 and does not automatically roll forward. See the product page for the full scope and license.
Questions about retainer profitability
Is every retainer with excess hours unprofitable?
No. Excess hours compare effort with agreed included hours. Profitability compares fees with a defined cost base. The February example exceeds scope but still has a positive 41.4% direct margin.
Can unused included hours be treated as extra profit?
Do not add them as revenue. The fee total already contains the retainer. Assess the service commitment, client expectations and your capacity policy separately.
Should I divide total agency profit by the number of clients?
That would hide differences in delivery effort and cost. This walkthrough calculates each client-month from its own fees, logged labor and direct expenses. It leaves overhead allocation outside the calculation.
What if the client’s fees are zero?
The margin percentage has a zero denominator and should remain unavailable. Direct contribution can still show the cost of the work. Do not label an undefined rate as a healthy zero-percent margin.
Example and calculations: TemplateBase fictional planner data. External references explain general definitions and workflow only. No customer outcomes or industry margin benchmarks are claimed. Updated October 16, 2026.